


Trust HoldingStructure
A trust on top of a holding and operating company when control and succession sit with the stack.

- Trust
- Holding LLC
- Operating LLC
Publication Saver Formation in NY
What you see is what you pay! Start here, add only the products you want, or choose a bundle below to save.

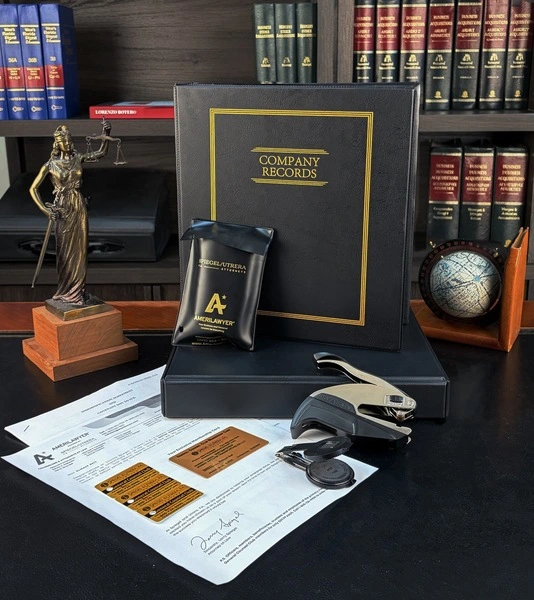
The printed records book and metal seal shown here are optional at checkout.
Included in Every Formation
Your service fee covers the formal documents, certificates, and resolutions banks and government agencies actually ask for, not just a state filing receipt. The Digital Corporate Book is included as a PDF; a printed book and metal seal can be added at checkout.
Benefits
Every formation is prepared, reviewed, and filed by a licensed legal team, the kind of accountability a DIY filing app can't offer.
File and forget services are everywhere. We're still with you a year from now: banking setup, contract review, compliance reminders, and legal questions answered by a real attorney or paralegal.

Mary Spiegel
President
Meet our attorneys
Every document is checked for accuracy before it leaves our desk.
We identify the right state filing fees for each entity required.
Deadlines tracked for you, so you never incur penalties or late fees.
Professional accountability you can't get when filing solo.
Multi state filings handled in a single, coordinated process.
Hand off the paperwork and get back to what actually matters.
Design Your Business Model
Start from a proven stack. Create your own if none of these match how you operate.
A trust on top of a holding and operating company when control and succession sit with the stack.
Keep owned assets in a holding company above the entity that takes day-to-day operating risk.
A holding and operating company plus a subsidiary for a distinct venture, brand, or asset.
Sketch a custom stack with licensed attorneys. The filings follow the structure you approve.
Create Your FrameworkFAQ
Still have questions? Talk to an attorney!
A corporation is a legal entity that is granted certain powers by the state. It is owned by shareholders who share in the profits and losses of the corporation. It is guided by directors that act like a legislature and decide important business decisions, which are then carried out by officers. Incorporation provides limited liability, tax advantages, marketing benefits, privacy options, easier transfer of ownership, and the ability to turn personal expenses into deductible business expenses.
The Limited Liability Company ("LLC") is a hybrid entity that combines limited liability protection with pass-through taxation. An LLC may be taxed as a partnership, corporation, or sole proprietorship depending on its members and elections. It allows flexibility in ownership, can have more than 100 members, accepts contributions in cash, property, or services, and avoids the restrictions imposed on Subchapter S Corporations.
Besides 501(c)(3) charitable corporations, 501(a) includes other tax-exempt organizations such as civic leagues, labor organizations, business leagues, social clubs, fraternal societies, credit unions, cemetery companies, veterans organizations, and various nonprofit associations that are exempt from federal income tax.
A 501(c)(3) organization is a non-profit corporation formed for charitable, religious, educational, literary, or scientific purposes. It does not pay federal or state income tax on profits related to its exempt purpose, under Section 501(c)(3) of the Internal Revenue Code.
A non-profit corporation is a state-incorporated entity with no equity owners and no income distributable to members, directors, or officers. Instead, it is controlled by members who elect a board of directors and is formed for nonprofit purposes.
A Sub Chapter S Corporation is a "plain vanilla" corporation at the state level that elects federal small business corporation status for tax benefits. It combines limited liability and corporate features with partnership-style tax treatment, passing profits and losses directly to owners.
A regular corporation pays corporate and shareholder-level tax, resulting in double taxation. A Sub Chapter S Corporation avoids this, as profits and losses flow directly to the owners. A small business corporation must meet requirements such as not being an ineligible corporation, having no more than 100 shareholders, only individuals/estates/trusts as shareholders, no nonresident aliens, and only one class of stock.
A Professional Service Corporation is formed by licensed professionals (e.g., doctors, accountants, engineers, architects) to provide professional services. Shareholders are typically limited to those licensed in the same profession, and stock transfers are restricted to eligible professionals or entities.


